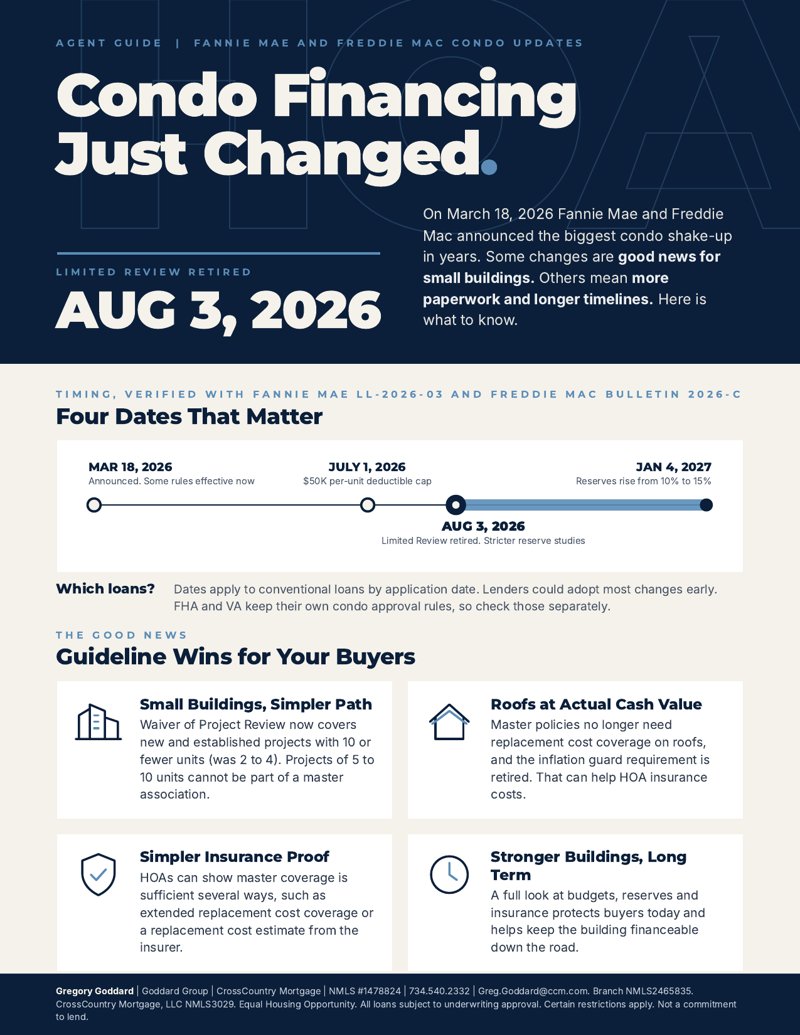
Four dates that matter
What changed
- Mar 18
Announced
Some rules effective now.
- $50K
Deductible cap
Per unit, from July 1, 2026.
- Aug 3
Full Review
Limited Review retired.
- 15%
Reserves
Up from 10%, Jan 4, 2027.
Before the offer
Condo checklist
- Check the project, not just the unit.
- Gather the HOA questionnaire, budget, reserve study and insurance early.
- Budget the HO-6 when there is a per-unit deductible.
- Add time to the contract for a Full Review.
- Ask about roof coverage at actual cash value.
- Not warrantable? Ask about portfolio and non-QM options.
Questions
Condo FAQ
Can I finance a condo in Michigan?
Yes. Conventional loans sold to Fannie Mae or Freddie Mac can finance condos, but the lender reviews the building, not just the unit. FHA and VA keep their own condo approval rules.
What changed for condo loans in 2026?
On March 18, 2026 Fannie Mae and Freddie Mac announced condo updates. Limited Review is retired for applications dated Aug 3, 2026 or later, so most established projects now need a Full Review or a Waiver of Project Review. See the guide.
Do small condo buildings have an easier path?
Often, yes. Waiver of Project Review now covers new and established projects with 10 or fewer units. Projects of 5 to 10 units cannot be part of a master association.
What are the new HOA reserve rules?
Under Full Review, the HOA budget must put at least 15% of annual assessment income into replacement reserves for applications dated Jan 4, 2027 or later, up from 10%. The rule measures what the HOA budgets each year, not the balance in the account.
Does the buyer need an HO-6 policy?
If the master policy has a per-unit deductible, the buyer needs an HO-6 policy covering at least that deductible. The per-unit deductible cap is $50,000, so price the HO-6 early.
What if the condo is not warrantable?
It is not over. Portfolio and non-QM options may still work, so ask Greg to look at the building.
Applies to conventional loans sold to Fannie Mae or Freddie Mac. FHA and VA condo rules differ. Requirements can change and lender overlays vary. Sources: Fannie Mae Lender Letter LL-2026-03 and Freddie Mac Bulletin 2026-C. More questions? See the homebuyer FAQ.